Mortgage and protection advice
Mortgage advice, with you at the heart of it.
Buying your first home, planning a move or reviewing your mortgage? Charlene can help you understand your options and decide on your next steps.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Choose your next step
Start with the situation closest to yours. Each guide explains what's involved and what to think about.
Buying your first home
Understand deposits, affordability and each step from first conversation to keys.
Find out moreMoving home
Weigh up porting your current deal against a new mortgage, and plan the timing.
Find out moreRemortgaging
Review your options before your current deal ends and you move to a standard rate.
Find out moreBuy-to-let
Talk through rental income, lender criteria, costs and the risks of letting.
Find out moreCommercial
Finance for business premises or investment property, and how it differs.
Find out moreProtection
Think through how your household would manage if illness, injury or death affected income.
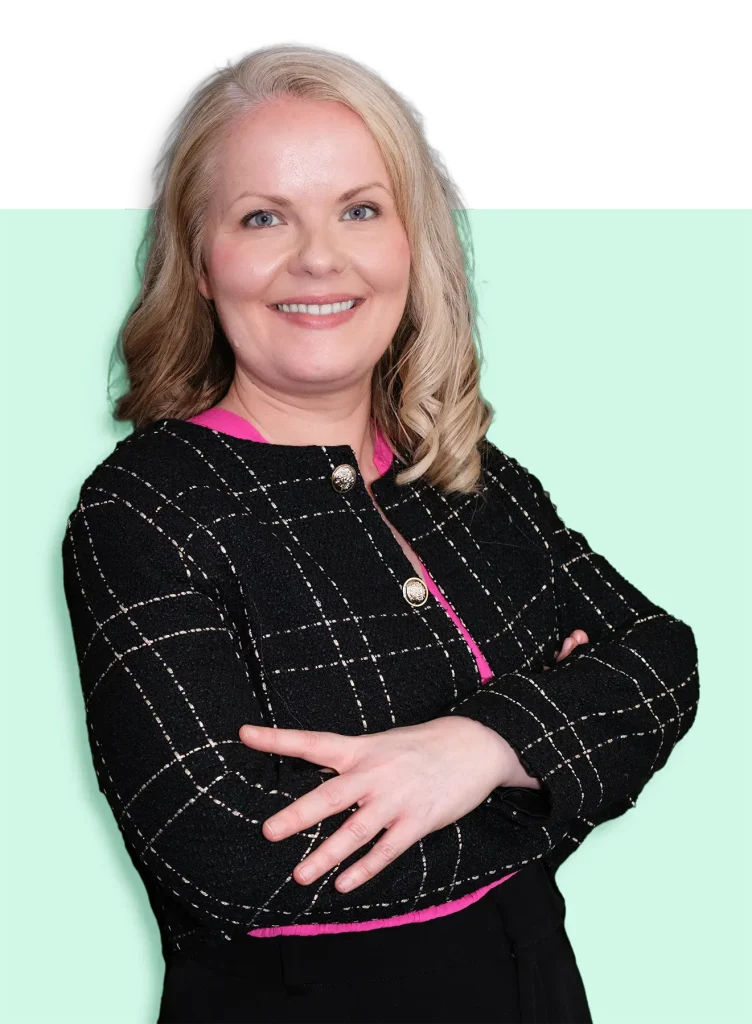
Find out moreMeet Charlene
Advice from someone who takes the time to understand you
Charlene has been a mortgage and protection broker for 25 years, with experience in each part of the mortgage industry. She's passionate about good quality advice, explained clearly, so you can make an important decision with confidence.
More about CharleneHow the advice process works
- 1
Initial conversation
Tell Charlene what you're planning and any questions on your mind.
- 2
Understanding your circumstances
Your income, outgoings, credit and future plans are reviewed together.
- 3
Explaining suitable options
Options are explained with their costs, limitations and reasons.
- 4
Supporting the application
Help with paperwork and keeping things moving towards completion.
Why people choose LNK
Clear explanations
Terms, costs and trade-offs explained in plain English, without assuming you already know.
Your whole picture
Advice that considers your future plans and household, not just today's rate.
One person to talk to
You deal with Charlene directly, from the first conversation onwards.
Protection
Protection alongside your mortgage
A mortgage is a long-term commitment. It can be worth thinking about how payments and household costs would be covered if illness, injury or death affected your income. Policies differ in what they cover and exclude.
Helpful answers
How much can I borrow for a mortgage?
It depends on your income, outgoings, credit history and deposit, and each lender assesses affordability differently. Charlene can give you an informed indication once she understands your circumstances.
When should I start looking at remortgaging?
Around three to six months before your current deal ends is often sensible, as many lenders let you secure a new deal in advance. Early repayment charges may apply if you leave a deal early.
What documents will I need?
Usually photo ID, proof of address, recent payslips or self-employed accounts, bank statements and evidence of your deposit. Lenders' requirements vary.
Do I need protection alongside my mortgage?
It isn't compulsory. Many people review life insurance, critical illness cover or income protection when they take on a mortgage, depending on their household and existing benefits.
How do I get started?
Send an enquiry or call Charlene. The first step is a conversation about your plans, so she can explain the options and what information would be needed.
Latest guidance
All guidesWhy choose a broker over AI? The human touch matters more than ever
Comparison sites and AI tools are a starting point. Here's why an experienced broker still makes the difference.
Read articleWhat happens if your rate comes down during the mortgage application process?
Mortgage rates change often. Here's how LNK Mortgages keeps an eye on your rate while your application goes through.
Read articleHelping you secure your future with flexible later life mortgages
A real example of how a later life lender can offer flexibility as your circumstances change.
Read articleLet's talk about your plans
Send an enquiry and Charlene will get in touch to understand your plans and explain what the next steps could look like.